Build an approval‑ready credit profile
Understand what’s driving your credit decisions, identify items that may be unfair or inaccurate, and take a structured next step toward stronger approvals and better terms.
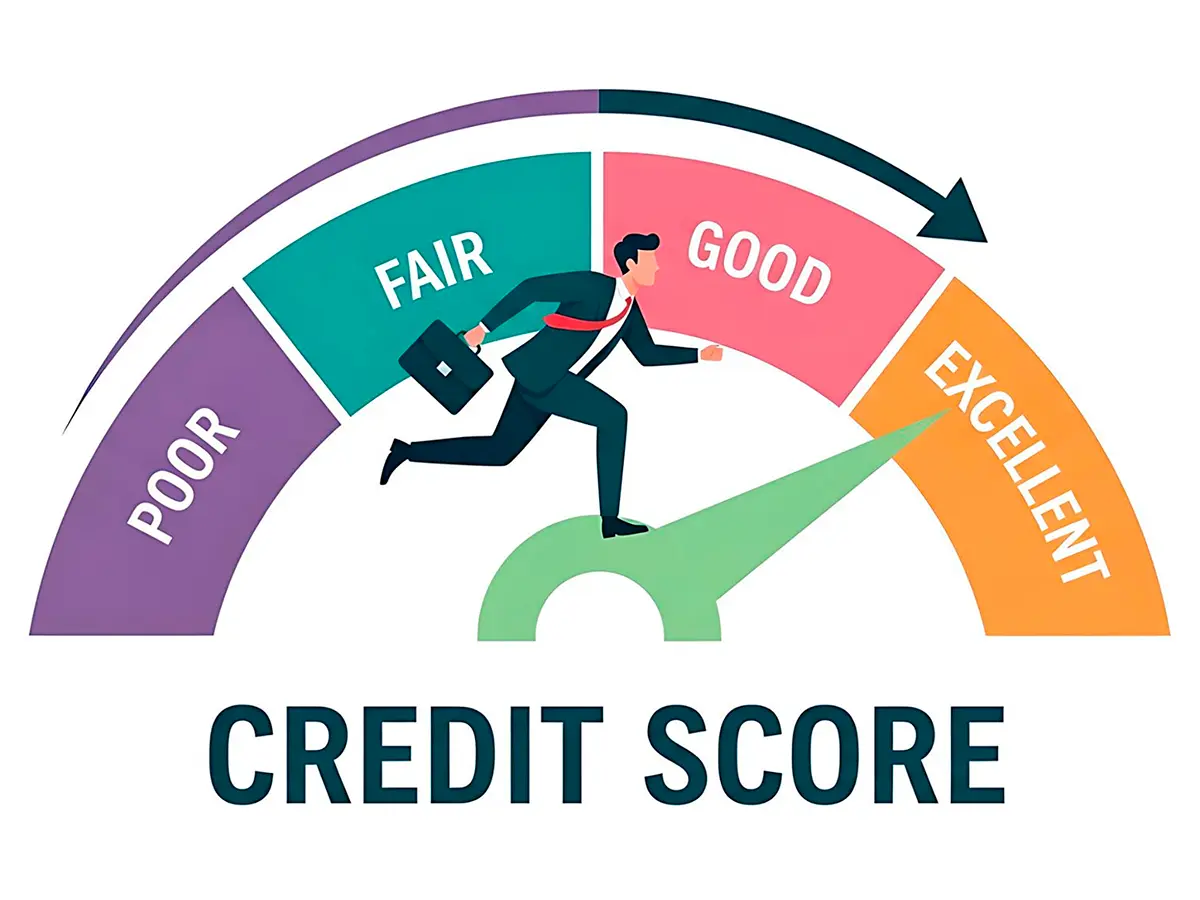
Built around established U.S. credit reporting practices and dispute procedures under the Fair Credit Reporting Act (FCRA). No unrealistic promises—just clarity, documentation, and structured credit improvement.
Unlock more options
Choose the outcome you care about. We’ll outline what improves it—and what to watch for—so you can move forward with confidence.
Your path to stronger credit
A stronger credit profile can mean better approval odds, improved loan terms, and more financial flexibility. Get a clear, no-fluff overview of what credit improvement can help you achieve — then take the next step when you're ready.
Credit decisions in the U.S. are typically influenced by payment history, utilization ratios, account age, recent inquiries, and the accuracy of reporting across major credit bureaus.
Even small inconsistencies can affect lending algorithms. A structured credit improvement approach focuses on verified data, responsible usage patterns, and consistent financial behavior.
*Results vary. This page does not guarantee outcomes.
How it works
A straightforward workflow used by reputable credit‑support programs: review, challenge what’s questionable, and build stronger habits while updates are processed.
Review your starting point
Clarify your goal and look at what’s currently affecting approvals and terms.
Identify what can be challenged
See what information is typically needed, what to expect next, and how the workflow usually looks.
Move forward
Continue to explore available options and take the next step toward better credit outcomes.
fixing my credit on my own: what actually worked for me
My first honest audit
I started by pulling all three credit reports and reading them like a bill I didn't want to overpay. I listed balances, due dates, APRs, and minimums in one place. Seeing everything at once calmed me down and showed me where small wins were hiding.
- I flagged two reporting errors: a late payment recorded twice and a closed store card marked open.
- I spotted high utilization on one card that was quietly dragging my score.
- I confirmed old accounts in good standing - valuable history I wouldn't touch.
Moves that made a visible difference
- Disputed inaccuracies. I submitted clear, short disputes with statements and dates. One fix landed in 30 days; the duplicate late fell off in the next cycle.
- Payment history first. I automated minimums on every card to dodge late fees, then paid extra on the highest APR balance. That alone saved me interest every month.
- Kept utilization low, mid-cycle. Instead of waiting until the due date, I made small payments before the statement cut. Once, while waiting at the grocery checkout, I got an alert that my balance was near 30%. I paid $38 in the app. It posted before the statement and nudged my utilization under the line.
- Secured card, used gently. I opened a small secured card, ran only gas through it, and paid twice a month. No drama, just steady on-time marks.
- Negotiated, politely. I called one issuer after 12 on-time payments and asked for a goodwill removal of an old late. I also requested a lower APR. I didn't get everything, but I did get a fee reversal and a small APR drop - real savings.
- Right-sized limits. I asked for a credit limit increase on a card that offered a soft pull only. It reduced my overall utilization without new debt.
The savings I actually felt
Cleaning up the late marks and trimming utilization moved my score enough that my car insurance premium dropped by $14 per month. Interest charges on my highest APR card shrank as my balance fell. A waived late fee and one APR reduction together covered a week's groceries. The financial relief was quiet, steady, and measurable.
What I track weekly
- Statement dates so I can pay before balances report.
- Credit alerts to catch new inquiries or weird activity fast.
- Snowball progress: the balance closest to zero gets extra each payday.
- Emergency fund transfers, even $10, to avoid running back to the card.
Reasonable limits to DIY
If you're facing active collections lawsuits, identity theft that keeps resurfacing, or income so unstable you can't cover minimums, doing it alone might not be enough. Free nonprofit counseling or legal help can be a smart safety net. I treated help as a tool, not a failure.
Patience, but with payoffs
My changes didn't pop overnight. The first 60 days built momentum; three to six months showed clear score movement; a year felt like a new baseline. I saved money, learned where my habits leaked cash, and kept my old accounts aging gracefully. The insight that mattered most: steady, boring steps beat big swings. And every tiny payment counted - especially the ones I made before the statement wrote my story for me.
Requesting a higher credit limit on your existing credit cards can improve your credit utilization ratio. Be careful with this if you think ...
Correct credit marks cannot be removed. I called and negotiated lower amounts due on my debt last year. My score went from 497 to 720 and I'm ...
You can work toward reducing your credit utilization ratio by paying down your account balances. It can also help if you open a new line of ...
Frequently asked questions
A clear next step — without the guesswork
See what’s impacting approvals and what may deserve a closer look.
Understand how disputes are structured and what documentation matters.
Improve utilization, consistency, and long-term credit stability.
See what improving your credit could change
Take a structured next step based on your current profile — and decide with clarity.